Time to maximize total corporate profits. Not minimize cash costs.
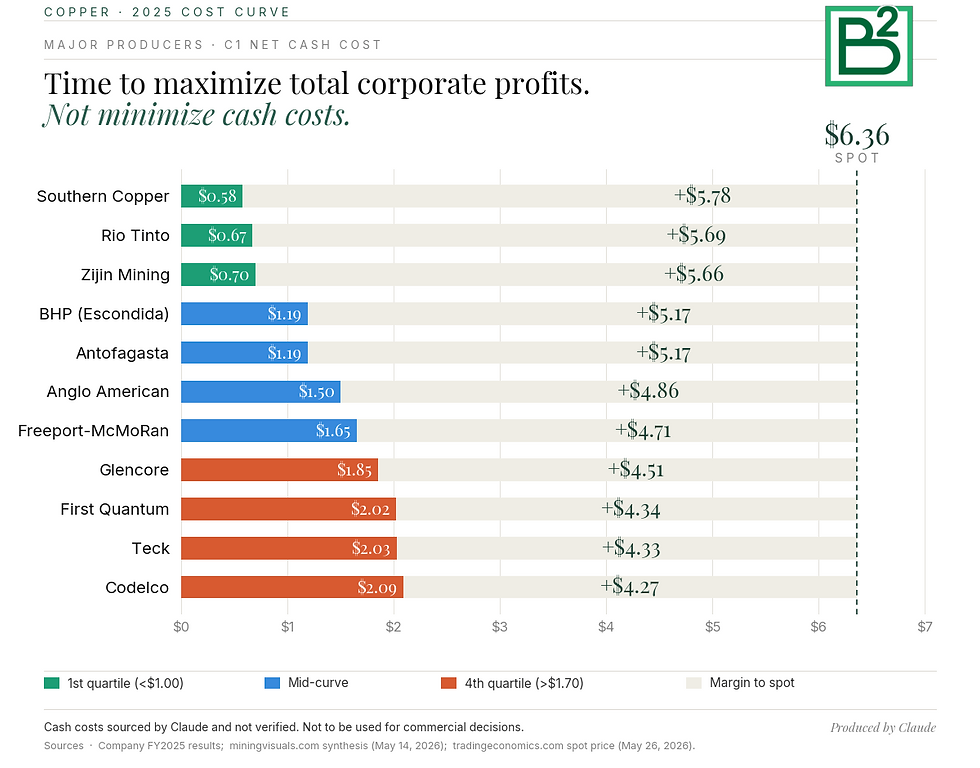
When cash costs are 22% of the copper price, it's time to maximize profits by shipping more marginal tonnes, by shifting the grade recovery curve.
I understand companies want to avoid appearing bloated. Still, with record-low TC/RCs and high prices, the rational approach is to pursue marginal recovery, drop the con grade, and pay slightly higher TC/RCs; the company will be much more profitable.
Going from 100,000 to 102,000 tonnes a year of copper, even if the marginal cost per tonne of that extra metal is $3.5 per pound or $7,000 per tonne, is still pure margin, with copper in the 13k range. But Wall Street sees inflation in cash costs and freaks out.
The thing is, when cash costs are under 25% of the sale price, it makes sense to take operational advantage of that margin and find extra “expensive” tonnes. It makes sense, especially if you can temporarily operate that overflow.
This world is changing, and cash costs were rational to protect when copper was trading close to cost, but now the goal should be maximum profit and revenue per tonne of contained copper, which requires shifting the grade recovery curve.

Comments